Proof of Insurance in a Dry Bag
A soaked document is no help when a trooper, land manager, rental shop, or crash investigator asks for proof of insurance. Alaska ATV and UTV riders also need to know whether their policy covers the kind of riding they plan to do. Keep usable proof protected, but first confirm what your insurance covers and when it is required.
Why Carry Proof on an Alaska ATV or UTV
Insurance paperwork and permission to ride are separate things. Registration, land permits, local road rules, and insurance answer different questions. A decal does not prove insurance, and an insurance card does not authorize access to land or a road.
When an APV is operated on a public roadway where that travel is allowed, liability insurance requirements apply. That does not mean every road is open to ATVs or UTVs. Local restrictions and road rules still matter; check Alaska APV Road Rules Explained and Alaska Communities That Ban APV Road Use before planning a route. For the insurance requirement itself, see Alaska Requires Liability Insurance for an APV.
Off-road requirements can depend on where and how you ride. A private landowner, rental operator, event organizer, or agency may set conditions beyond state road requirements. The Alaska’s Statewide General Permit for ATV Use is about authorized use of certain state land; it is not an insurance policy and does not replace permission for other land. Review Alaska Land Ownership and Who to Ask when a route crosses ground managed by different owners or agencies.
Carrying proof is useful even when you are not sure it will be requested. It can help you:
- Show that a required liability policy is in force.
- Provide policy and insurer details after a collision.
- Give accurate information to another rider or a property owner.
- Meet a rental, event, or land-access condition.
- Avoid relying on a phone that has lost signal, battery, or screen access.
The key is to carry proof that is current and legible, and to understand its limits. An insurance card may identify the policy and vehicle but not spell out every exclusion. It is evidence of insurance, not a guarantee that a particular injury, collision, or machine repair will be covered.
Confirm What Your Policy Covers Before You Ride
Do not assume that an ATV or UTV policy covers every use just because the machine is insured. A policy may distinguish between road use and off-road recreation, or set conditions on who may operate the machine, what it is used for, and where it is ridden. A policy for a privately owned quad may not apply to a borrowed or rented machine.
Before riding, contact your insurer and ask questions about the specific machine and trip. Give a clear description: ATV or side-by-side, who will drive, whether the route includes any public roadway, and whether the use is recreational, work-related, or part of a guided or organized ride. Ask whether liability coverage applies and whether the policy also covers damage to your machine, theft, medical costs, or injuries to passengers. These are different kinds of protection and may have different terms.
| What to check | Why it matters | What to confirm |
|---|---|---|
| Named machine and policy status | Proof should match the vehicle being used and show current coverage | Whether the machine is listed and the policy is active for the planned ride |
| Public-road use | Road travel may trigger insurance requirements, but not every road allows APVs | Whether the policy covers the permitted road use and what proof to carry |
| Off-road use | A road-oriented policy may not cover all recreational riding | Whether riding on trails, public land, or private land is covered |
| Driver and passengers | Coverage can depend on who operates or rides in the machine | Any driver, age, passenger, or household restrictions |
| Borrowed or rented machine | Your own policy may not automatically cover another owner’s machine | Which policy applies and what the rental or owner requires |
| Damage to the machine | Liability coverage generally addresses claims against the insured, not every repair to the insured vehicle | Whether collision, comprehensive, or other damage coverage applies |
| Emergency response and recovery | Towing or recovery is not necessarily part of ordinary liability coverage | Whether the policy includes assistance and what limits or exclusions apply |
Ask the insurer to explain exclusions in plain language. For example, a policy might treat public-road use differently from riding on a trail, or might limit coverage when a machine is used for business. Do not rely on a verbal guess from someone who cannot see the policy. If the answer affects whether you will take the machine, request written confirmation or ask the insurer to point to the relevant policy terms.
Out-of-state riders should be especially careful about reciprocity. A registration decal or insurance card from another state does not automatically settle whether a machine may be operated in Alaska, whether a local road is open to it, or whether the policy covers the ride. Check Does an Out-of-State Machine Need Alaska Registration? and Alaska Rules for an Out-of-State Machine for the separate registration and operating questions. Then ask your insurer about coverage in Alaska and on the type of terrain you plan to ride.
If you are renting, do not assume your personal auto policy covers the rental ATV or UTV. Ask the rental company what insurance is included, what remains your responsibility, and whether you must show separate proof. Read the agreement before departure, not after an incident. Alaska Rental Waivers You Sign explains why a waiver and an insurance policy are not interchangeable.
Pack Proof So It Survives Water, Mud, and Cold
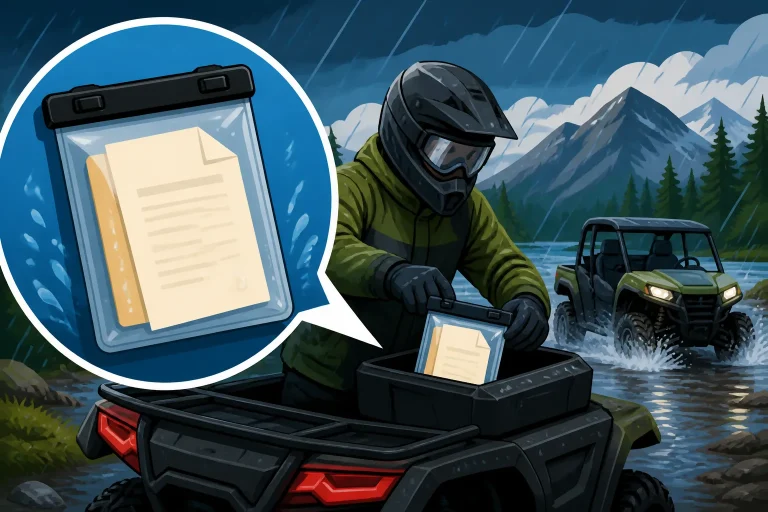
A small waterproof pouch or dry bag is a practical way to protect paper documents from rain, spray, mud, and a wet glove compartment. Choose a size that closes securely and lets you read the contents without taking them out in bad weather. An inexpensive dry bag from a retailer such as Amazon may work, but the closure and condition matter more than the label.
A useful document kit is compact. Carry only what you may need, keep it separate from loose tools and food, and make sure it can be reached without unloading the machine. Include:
- Current insurance proof. Carry the insurer’s current card or other official proof, with the policy dates and vehicle details readable.
- A second copy. Keep a backup in a separate dry location, such as a sealed compartment or with another rider in your group. A second copy is only useful if it is also current.
- Insurer contact details. Save the insurer’s claims number and policy contact information on paper as well as in your phone.
- Emergency contacts. Include the names and numbers of people who should be notified if you are injured or delayed.
- Relevant machine details. If helpful for a claim, record the machine’s identifying information separately and keep it protected. Avoid carrying unnecessary sensitive documents.
Do not put the only copy in a pocket that may be removed with a jacket, or in an exposed cargo box that can fill with water. Check the bag’s seal before setting out. If it has been torn, punctured, or left open, replace it; a bag that looks waterproof is not protective if its closure no longer works.
Keep a digital copy too, but treat it as a backup rather than your only plan. Save the document securely on your phone so it can be opened without a data connection. A screenshot may be easier to access than a file that requires signing in, but it should show the current dates and necessary details. Protect the phone with a case, carry a power bank if appropriate, and remember that a dead or damaged device cannot display anything.
For group rides, each rider should know where their own proof is and how to access it. Do not assume the lead rider’s documents will be available if the group separates. If one person carries a shared backup, another rider should still have a way to identify the insurer and contact them.
What to Do When Someone Asks for Proof
If an officer or another authorized person asks for proof, stay calm and provide the document requested. Keep your hands visible, follow instructions, and avoid reaching into a bag or compartment without explaining what you are doing. If the paper copy is wet or hard to read, offer the protected backup or digital copy and explain where the current document is stored.
After a crash, prioritize safety and medical needs before paperwork. Once it is safe, exchange contact and insurance details with the other parties as appropriate, record the location and circumstances, and take photos if doing so is safe. Do not admit fault or speculate about coverage. Report the incident to your insurer promptly and follow its instructions. A policy card gives contact information, but the insurer determines how a claim is handled under the policy.
If the ride is on private or managed land, insurance proof does not settle an access dispute. Show the relevant permit or permission if requested, and do not continue across land when you are unsure who controls it. Asking Who Owns the Ground First and A Trailhead Pass Is Not a Land Permit cover two common misunderstandings: access permission and insurance are separate requirements.
Before leaving home, use this quick check:
- Is the policy active for the date of the ride?
- Does it cover this machine, driver, and intended use?
- Have you checked coverage for any public-road segment?
- Are required road permissions and local rules handled separately?
- Is a legible paper copy sealed in a dry bag?
- Can you access a backup without cell service?
- Do other riders know how to reach you and the insurer?
A dry bag is a small piece of preparation, not a substitute for confirming coverage. Check your policy before the trip, carry proof where it stays readable, and treat insurance, registration, permits, and road access as distinct parts of a legal and well-planned ride.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.